What Is a Good 401(k) Match? 2026 Benchmarks
Calculate your employer 401(k) match and compare it with Vanguard's latest benchmark: a 4.0% median and 4.7% average maximum promised match.
401(k) Employer Match Calculator
Annualized estimate using 2026 IRS limits. Compare the result with your plan document.
Model the match percentage and deferral cap stated in your plan document.
This is an annual formula estimate, not a benefits determination. Eligibility, the plan's compensation definition, payroll timing, true-up provisions, catch-up matching and other contributions can change the deposited amount. Sources: IRS safe harbor formula guidance and 2026 contribution limits.
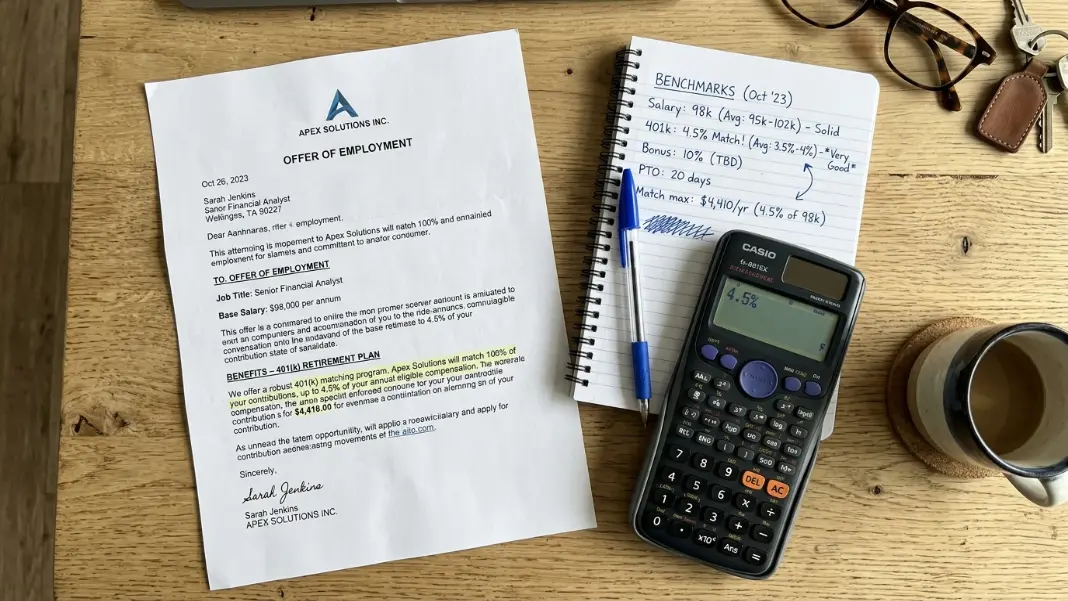
A good 401(k) match cannot be judged from a headline such as “50% match” or “up to 6%” alone. You need the match rate, the employee-deferral cap, eligible compensation, and the amount you will actually defer. A 50% match on the first 6% of pay and a 100% match on the first 3% both promise a maximum employer contribution equal to 3% of pay, but they produce different amounts below the cap.
Use the calculator above to turn a plan formula into annual dollars. Then compare its maximum promised match as a percentage of pay with the current benchmark below. The benchmark describes Vanguard-administered defined contribution plans, not every US employer and not the amount every participant actually received.
Average and Median 401(k) Match: Latest Available Benchmark#
Vanguard's How America Saves 2026 reports estimated 2025 plan data. Among Vanguard plans with a single- or multitier matching formula:
| Benchmark | 2025 result | What it measures |
|---|---|---|
| Average maximum promised match | 4.7% of pay | Average of the most each formula promised when the employee deferred enough |
| Median maximum promised match | 4.0% of pay | At least half of measured plans were at or below this value and at least half were at or above it |
| Median deferral needed for the full match | 6.0% of pay | Employee deferral required to obtain the formula's maximum |
| Average deferral needed for the full match | 6.4% of pay | Average employee threshold across measured formulas |
The report also found that 80% of plans, covering 79% of participants, required an employee deferral from 4.0% through 6.99% of pay to obtain the maximum match.
These are promised maximums, not average deposits. A participant who defers below the required rate receives less under a matching formula. Eligibility dates, the plan's compensation definition, annual limits, per-pay-period calculations, employment changes, and true-up provisions can also make the amount deposited different from the headline maximum.
Most Common 401(k) Match Formulas in the Latest Data#
Vanguard administered more than 100 distinct matching formulas in 2025. These were the five most frequently used among plans offering a match:
| Match formula | Share of plans offering a match |
|---|---|
| 50% on the first 6% of pay | 12% |
| 100% on the first 3%, then 50% on the next 2% | 9% |
| 100% on the first 6% of pay | 9% |
| 100% on the first 5% of pay | 7% |
| 100% on the first 4% of pay | 7% |
The 50%-on-6% design was the most frequently used single formula, but it appeared in only 12% of plans offering a match. “Most frequent” does not mean a majority or the median formula. A maximum promised match of 4% is the better midpoint benchmark for this sample; a higher percentage is above that midpoint, but it still does not make one job offer better by itself. Salary, vesting, plan fees, investment options, health coverage, and the employee deferral required to earn the match all matter.
How to Calculate the Real Value of a 401(k) Match#
For a simple single-tier formula:
Employer match = Eligible compensation
               × min(Employee deferral rate, matched deferral cap)
               × Employer match rate
For a 50% match on deferrals up to 6% of pay at a $75,000 salary:
| Employee deferral | Employee amount | Employer amount | Employer % of pay |
|---|---|---|---|
| 3% | $2,250 | $1,125 | 1.5% |
| 6% | $4,500 | $2,250 | 3.0% |
| 10% | $7,500 | $2,250 | 3.0% |
The match stops increasing after the employee reaches the 6% matched-deferral cap. Deferring more can still increase retirement savings, but it does not increase this employer match.
Now compare a 100% match on the first 3% of pay:
- At a 3% employee deferral, the employer contributes $2,250.
- At a 6% employee deferral, the employer still contributes $2,250.
Both formulas have the same 3% maximum promised value. The dollar-for-dollar formula reaches it with a lower employee deferral, which can matter when cash flow is constrained.
Five Checks That Change What a Match Is Worth#
1. Required employee contribution
A 6% maximum match that requires a 12% employee deferral is not directly comparable with a 6% dollar-for-dollar match. Calculate the employer dollars at the contribution rate you can realistically maintain.
2. Vesting
Employee elective deferrals are always fully vested. Employer contributions may vest immediately or under a permitted schedule. Under a three-year cliff schedule, the employer-funded balance is 0% vested before three years of service and 100% vested after completing three years; it does not vest proportionally. A two-to-six-year graded schedule vests in steps. Traditional safe harbor contributions are generally immediately vested, while QACA safe harbor contributions can require up to two years for full vesting. See the Safe Harbor 401(k) Match guide for those distinctions.
3. Per-pay-period matching and true-up
Some plans calculate the match each payroll period. If an employee reaches the annual deferral limit early or changes the deferral rate during the year, some pay periods may have no matched contribution. A year-end true-up can reconcile the result, but not every plan provides one. Check the Summary Plan Description instead of assuming an annual calculation.
4. Eligible compensation
The plan document defines which compensation is matched. Base salary, bonuses, commissions, overtime, or compensation earned before eligibility may be treated differently. In 2026, compensation used for qualified-plan contribution calculations is generally limited to $360,000.
5. Annual contribution limits
Employer contributions do not consume the employee's regular $24,500 elective-deferral limit for 2026. They do count toward the annual-additions ceiling, which is generally the lesser of $72,000 or 100% of compensation. Other employer, employee after-tax, and allocated contributions can use part of that ceiling; eligible catch-up contributions are treated separately.
How to Compare Two Job Offers#
Use the same salary and three employee-deferral scenarios for both offers:
- The minimum you can comfortably defer.
- The rate you expect to maintain.
- The rate required to receive each plan's full match.
For each scenario, record the annual employer dollars, employee dollars required, vesting after your expected tenure, and whether a true-up exists. Then compare the full compensation package. This avoids two common errors: treating a match rate as a percentage of salary and valuing unvested employer contributions as if they are already yours.
If a plan combines a nonelective contribution and a match, calculate the pieces separately. For example, at $80,000 of eligible compensation, a 3% nonelective contribution provides $2,400 without an employee deferral. A separate 50% match on the first 4% can add up to $1,600, but only when the employee defers at least 4%. The maximum combined employer amount is $4,000—not $4,000 before the employee contributes.
What a Two-Percentage-Point Difference Can Become#
At $70,000 of constant annual compensation, the difference between a 2% and 4% employer contribution is $1,400 per year. If deposited monthly at the beginning of each month for 25 years and compounded at a constant 7% annual rate, that difference grows to approximately $95,000 before fees and taxes.
That is a deterministic illustration, not a forecast. Actual returns vary, salaries and limits change, vesting may reduce the amount kept, and fees lower the ending value. The useful point is that a recurring match difference compounds; the exact future amount is uncertain.
Sources and Scope#
The benchmark figures come from Vanguard's How America Saves 2026 report, using estimated 2025 data from Vanguard-administered defined contribution plans. Current dollar limits come from the IRS 401(k) contribution-limit table. Vesting schedules are described in the IRS matching-contribution vesting guidance. Your plan document controls your actual formula, eligibility, compensation, vesting, and true-up terms.
There is no universal cutoff. In Vanguard's estimated 2025 plan data, the median maximum promised match was 4.0% of pay and the average was 4.7%. Use those as scoped reference points, then compare the employee deferral required, vesting, eligible compensation, true-up rules, plan fees, and the rest of the compensation package.
The latest Vanguard report found an average maximum promised match of 4.7% of pay and a median of 4.0% among measured plans with single- or multitier match formulas. Those figures describe the formula's maximum, not the average amount participants actually received, and they are not a census of every US employer.
It was the most frequently used single formula in Vanguard's estimated 2025 data, appearing in 12% of plans offering a match. It promises a maximum employer contribution of 3% of pay when the employee defers at least 6%. It should not be called the majority formula or the median formula because many other designs were used.
Not necessarily. It could mean a 100% match on the first 5% of pay, a 50% match on the first 10%, or another formula whose maximum equals 5% of pay. Read both the employer match rate and the employee-deferral cap in the plan document.
Calculate employer dollars at the same salary and at your minimum, likely, and full-match deferral rates. Then apply each plan's eligible-compensation definition, vesting schedule, payroll method, annual limits, and true-up provision. Compare the employer dollars you are likely to receive and keep, not just the headline percentage.
A 3% maximum is below the 4.0% median maximum in Vanguard's estimated 2025 data. Whether it is attractive depends on the employee deferral required, vesting, salary, plan costs, investments, and total compensation; the percentage alone is not enough to judge the offer.
Written by
Hassaan Rasheed
Web Developer & Content Researcher
Hassaan builds calculators and writes source-linked guides across the site's subject areas. Calculator methods and reference data are documented in each guide so readers can verify the underlying sources.
About the author and methods